
Limited-Time Offer: Enjoy 50% Savings! - Ends In 0d 00h 00m 00s Coupon code: 50OFF
Welcome to QA4Exam
Logo

- Trusted Worldwide Questions & Answers

Exam dumps demo

CPA-Regulation Exam Dumps and Practice Questions

Preview page 1 of 14 with real questions 1 to 5 from the full 69-question AICPA set.

AICPA CPA-Regulation Dumps - Pass CPA Regulation Exam in First Attempt 2026

The AICPA CPA-Regulation exam is part of the Certified Public Accountant certification and focuses on the regulation knowledge expected from accounting professionals. It is designed for candidates who want to demonstrate a strong understanding of tax, business law, ethics, and related regulatory concepts. Passing this exam is an important step for anyone pursuing the CPA credential and building credibility in the accounting profession. A solid preparation plan can help you approach the exam with confidence and improve your chances of success.

# Exam Topics Sub-Topics Approximate Weightage (%)
1 Area I - Ethics, Professional Responsibilities and Federal Tax Procedures Ethical standards, professional responsibilities, tax procedures, filing and compliance rules 15%
2 Area II - Business Law Contracts, agency, debtor-creditor relationships, business structure rules 20%
3 Area III - Federal Taxation of Property Transactions Asset basis, gains and losses, like-kind exchanges, property dispositions 20%
4 Area IV - Federal Taxation of Individuals Individual income tax, deductions, credits, tax preparation, planning strategies 25%
5 Area V - Federal Taxation of Entities Partnerships, corporations, entity taxation, tax preparation, planning strategies 20%

The exam tests your ability to apply regulatory and tax concepts to practical situations, not just memorize definitions. Candidates need a clear understanding of rules, procedures, and business law principles, along with the ability to analyze tax scenarios and choose the correct response under exam conditions.

Actual AICPA CPA-Regulation Exam Questions

Question 1

Darr, an employee of Sorce C corporation, is not a shareholder. Which of the following would be included in a taxpayer's gross income?

Correct answer: D

Choice 'd' is correct. An individual receiving common stock for services rendered must recognize the fair market value as ordinary income. Any dividends received on that stock would also result in income recognition.

Choice 'a' is incorrect. Employer-provided medical insurance is a tax-free fringe benefit.

Choices 'b' and 'c' are incorrect. Gifts and inheritances are both tax-free to the recipient. (Remember tax is often paid by the person giving the gift or the estate at death.)
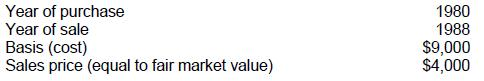

Question 2

Doris and Lydia are equal partners in the capital and profits of Agee & Nolan, but are otherwise unrelated. The following information pertains to 300 shares of Mast Corp. stock sold by Lydia to Agee & Nolan:

The amount of long-term capital loss that Lydia realized in 1988 on the sale of this stock was:

Correct answer: A

Choice 'a' is correct. $5,000 long term capital loss 'realized' in 1988 by Lydia. Be careful, and always check the question being asked. In this case, the question is how much of a capital loss Lydia realized in 1988.

Choice 'b' is incorrect. $3,000 represents the portion of the $5,000 realized loss that would currently be recognized unless there were additional capital transactions resulting in gains. Remember that the deduction for capital losses for an individual is limited to $3,000 each year.

Choice 'c' is incorrect. $2,500 represents the pre-1986 portion of the $5,000 realized loss that would have given rise to a recognized loss. Pre-1986 law required $2 of net long term loss to give the benefit of $1 of tax deduction. Current law gives a dollar-for-dollar deduction limited to $3,000 in any year.

Choice 'd' is incorrect. $0 would have been the amount of loss recognized if Lydia owned more than a 50% interest in the partnership. Losses realized on transactions between a partnership and a partner owning more than a 50% interest are not deductible as the parties would be considered related and any realized loss would be disallowed.


Question 3

Freeman, a single individual, reported the following income in the current year:

Guaranteed payment from services rendered to a partnership $50,000

Ordinary income from a S corporation $20,000

What amount of Freeman's income is subject to self-employment tax?

Correct answer: C

Choice 'c' is correct. Guaranteed payments are reasonable compensation paid to a partner for services rendered (or use of capital) without regard to his ratio of income. Earned compensation is subject to selfemployment tax. Payments not guaranteed are merely another way to distribute partnership profits. The ordinary income reported from an S corporation are taxable income to the individual or their own individual tax return but is not subject to self-employment tax. The ordinary income reported from a partnership may be subject to self-employment tax (if to a general partner).


Question 4

The uniform capitalization method must be used by:

I Manufacturers of tangible personal property.

II Retailers of personal property with $2 million dollars in average annual gross receipts for the 3 preceding years.

Correct answer: A

Choice 'a' is correct. I only.

Rule: The uniform capitalization rules apply to the following:

1. Real or tangible personal property produced by the taxpayer for use in a trade or business.

2. Real or tangible personal property produced by the taxpayer for sale to customers.

3. Real or personal property acquired by the taxpayer for resale.

4. However, the uniform capitalization rules do not apply to property acquired for resale if the taxpayer's annual gross receipts for the preceding three tax years do not exceed $10,000,000 (not $2 million).


Question 5

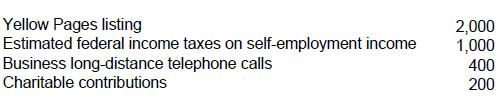
Rich is a cash basis self-employed air-conditioning repairman with 1993 gross business receipts of $20,000. Rich's cash disbursements were as follows:

What amount should Rich report as net self-employment income?

Correct answer: A

Choice 'a' is correct. Deductions to arrive at net self-employed income include all necessary and ordinary expenses connected with the business. Estimated federal income tax payments are not an expense. Charitable contributions by an individual are only deductible as an itemized deduction on Schedule A. This assumes the contribution was not made with the 'expectation of commensurate financial return.'

Choice 'b' is incorrect. Charitable contributions are an itemized deduction unless there is an expectation of commensurate financial return.

Choice 'c' is incorrect. Federal income taxes paid are not a deductible expense.

Choice 'd' is incorrect. Charitable contributions are an itemized deduction unless there is an expectation of commensurate financial return. Federal income taxes paid are not a deductible expense.


Unlock all AICPA CPA-Regulation questions

Full exam access, validated answers, and unlimited practice with no download limits.

How QA4Exam.com Helps You Pass

QA4Exam.com provides CPA-Regulation Exam PDF materials with actual questions and answers, along with an Online Practice Test designed to mirror the exam experience. These resources help you study with up-to-date questions, verified answers, and a format that supports real exam simulation. The practice test also helps you improve time management and get comfortable with question patterns before exam day. With focused preparation, you can strengthen weak areas and work toward passing the AICPA CPA-Regulation exam on your first attempt.

FAQ

1. What is the AICPA CPA-Regulation exam?

It is the regulation section of the Certified Public Accountant certification and covers ethics, business law, and federal taxation topics.

2. Is the CPA-Regulation exam difficult?

It can be challenging because it combines legal, ethical, and tax concepts, so candidates need both understanding and application skills.

3. Can I pass CPA-Regulation with only braindumps?

Braindumps alone are not the best approach. They are most effective when used with study and review so you understand the concepts behind each question.

4. Do I need hands-on experience to pass this exam?

Hands-on experience can help, but the exam mainly measures your knowledge of regulation topics and your ability to apply them to exam questions.

5. Are QA4Exam.com dumps enough, or do I need other resources?

QA4Exam.com exam PDF and Online Practice Test are strong preparation tools, and many candidates use them to reinforce study and test readiness.

6. How do QA4Exam.com practice tests help with first-attempt success?

They help you practice real exam style questions, check verified answers, and improve time management so you can enter the exam with more confidence.

7. What format do QA4Exam.com products come in?

QA4Exam.com offers an Exam PDF with questions and answers and an Online Practice Test for interactive exam simulation.